Get new articles by email:

Oblivious Investor offers a free newsletter providing tips on low-maintenance investing, tax planning, and retirement planning.

Join over 24,000 email subscribers:

Articles are published every Monday. You can unsubscribe at any time.

Financial Planning Roundup: Guest on The Long View Podcast

I recently had the opportunity to join Christine Benz and Amy Arnott for Morningstar’s The Long View podcast. We discussed my new book and a variety of themes relating to cybersecurity, as well as how to keep ourselves (and our family members) safe as we age.

Other Recommended Reading

Thanks for reading!

Tax Treatment of Selling Trading Cards (Are They Collectibles?)

A reader writes in, asking:

“I recently sold some old Magic the Gathering cards for a considerable sum of money. I know reddit is not the place to go for tax advice, but everybody there says this would count as a sale of of a ‘collectible’ whereas I’m getting mixed answers from AI. I’ve tried looking on the IRS website but cannot find any actual answers there. Please help!”

Firstly, let’s provide some background for anybody not familiar with why this question matters. For the most part, long-term capital gains are taxed at favorable tax rates (i.e., tax rates lower than the ordinary income tax brackets). However, long-term capital gains from the sale of collectibles are taxed at your ordinary income tax rate, subject to a 28% maximum rate. (That is, if you’re in the 0-24% brackets, a long-term capital gain from the sale of collectibles would be taxed at your ordinary income tax rate, and if you’re in the 32-37% tax bracket, a long-term capital gain from the sale of collectibles would be taxed at a 28% rate.)

In other words, if you’ve just sold something for a gain, you would prefer that it be something that doesn’t count as a collectible.

Most people would consider Magic the Gathering cards, Pokemon cards, baseball cards, etc. to be firmly within the colloquial definition of the word “collectible.” People certainly have collections of baseball cards, Magic cards, Pokemon cards, etc. The category of games that includes Magic and Pokemon is often even referred to as a “collectible card game.”

And yet, what matters is not colloquial definitions but rather our tax law.

And the law itself points in the opposite direction. The relevant definition comes from IRC § 408(m), which states:

the term “collectible” means:

(A) any work of art,
(B) any rug or antique,
(C) any metal or gem,
(D) any stamp or coin,
(E) any alcoholic beverage, or
(F) any other tangible personal property specified by the Secretary for purposes of this subsection.

In other words, it’s a specific list of things. The wording is not that the term “collectible” includes those items (and therefore potentially includes other items as well). Rather, the wording is that “collectible” means specifically the things on that list. And there’s no broad catch-all statement. The closest thing to a catch-all is paragraph (F), which indicates that the Secretary has to specify the property in question as a collectible.

So what has the Treasury Department specified as collectibles? Not very much, it turns out.

In a 1984 proposed regulation, the Treasury stated that the term “collectible” means:

(1) Any work or art,
(2) Any rug or antique,
(3) Any metal or gem,
(4) Any stamp or coin,
(5) Any alcoholic beverage,
(6) Any musical instrument,
(7) Any historical objects (documents, clothes, etc.), or
(8) Any other tangible personal property which the Commissioner determines is a “collectible” for purposes of this section.

In other words, relative to the law itself, the proposed regulation added musical instruments and historical documents. But still no wording regarding trading cards or any number of other things that we’d often refer to as collectibles. (Also, for what it’s worth, that 1984 proposed regulation was never finalized.)

More recently, in 2023, the IRS specified that NFTs (nonfungible tokens) would be considered collectibles if the underlying asset is itself a collectible. But that’s not relevant here either.

I cannot find anything whatsoever indicating that the IRS has ever publicly indicated that trading cards are collectibles, even though that’s what you’d intuitively assume would be the case. They would be collectibles if you consider them to be works of art or historical objects, but that seems like a stretch in most cases.

In a 2023 letter to the IRS, the New York State Bar Association stated:

We observe that under current law, section 408(m) may not apply to many tangible assets commonly understood as collectibles, including sports and trading cards, dolls and figurines, comic books, magazines, stuffed animals and video games. The policy arguments for extending section 408(m) to NFTs presumably apply with equal force to such tangible assets, which have been bought and sold for prices comparable to the prices commanded by the most sought-after NFTs. Yet although section 408(m)(2)(F) authorizes Treasury to identify additional categories of tangible collectibles, Treasury has never exercised that authority.

So if you sell something that we’d typically think of as a collectible, but which the law does not include in the definition of a collectible, reporting it as a sale of a collectible and paying the higher tax rate is probably the safest thing to do, if you want to be 100% sure that you won’t have your tax bill adjusted upward at a later date. But at the same time, the law says what it says. And filing a tax return that is in keeping with what the law says is generally a pretty reasonable thing to do.

For More Information, See My Related Book:

Book3Cover

Taxes Made Simple: Income Taxes Explained in 100 Pages or Less

Topics Covered in the Book:
  • The difference between deductions and credits,
  • Itemized deductions vs. the standard deduction,
  • Several money-saving deductions and credits and how to make sure you qualify for them,
  • Click here to see the full list.

A testimonial from a reader on Amazon:

"Very easy to read and is a perfect introduction for learning how to do your own taxes. Mike Piper does an excellent job of demystifying complex tax sections and he presents them in an enjoyable and easy to understand way. Highly recommended!"

Financial Planning Roundup: Successful Book Launch

Firstly, thank you to everybody who purchased the new book Household Cybersecurity over this last week! If you have any questions about the material, feel free to ask, as you’re probably not the only person with that same question.

If you found the book to be helpful, please consider leaving a review on Amazon (or Goodreads), as that’s the best way to help others find the book.

Other Recommended Reading

Thanks for reading!

New Book — Household Cybersecurity: a CPA’s Guide to Protecting Your Accounts and Personal Information

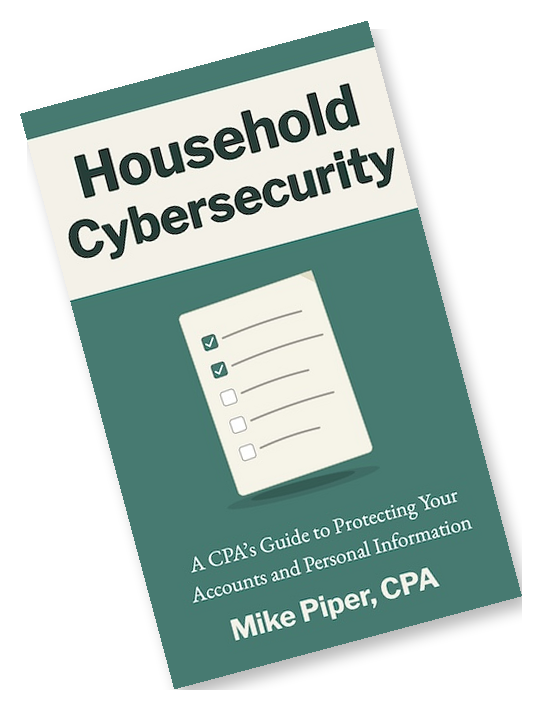
Household Cybersecurity book coverI’m excited to announce that my latest book is now available on Amazon:

As we’ve discussed here lately, data from the FBI and FTC indicate that cybercrime and fraud have been growing at an alarming rate in recent years. In part, that’s because the tools available to the bad guys are getting better and better every year.

Unfortunately, some people aren’t even aware of the problem. They’re just following the same cybersecurity practices that they were following a decade ago.

Some people do recognize the problem, but they aren’t really sure what they should be doing to protect themselves.

And finally, some people recognize the problem, and they’re actively working on improving their security, but they have a lot of questions about newer tools, what is safe, what isn’t safe, etc.

My goal is for this book to be helpful to all three groups.

Most cybersecurity advice boils down to telling you to be careful: be suspicious of that email, don’t click that link, etc. That is good advice, but it doesn’t go far enough, because it only works if you get it right every single time, for the rest of your life.

A primary theme of this book is that, whenever possible, we want to reduce the degree to which your security depends on making the right judgment, in the moment. The goal is to put protections in place that hold up even when somebody in the household makes a mistake. Because, eventually, somebody in the household will make a mistake.

It’s similar to what we do with saving and investing. A plan that relies on somebody remembering to make manual retirement account contributions every month is much less likely to be successful than a plan in which retirement account contributions are automated. In both cases, the idea is to create a system to reduce our dependence on perfect behavior.

The Focus

As is hopefully clear from the title, this isn’t a book about enterprise cybersecurity. Rather, the question at hand is: what does an ordinary household actually need to know and do to protect their money and personal information?

If you’ve been reading this blog for a while, you know that cybersecurity isn’t my primary profession. But I’ve spent considerable time studying the subject: I’ve earned CompTIA’s Security+ certification, ISACA’s Cybersecurity Audit Certificate, and the AICPA’s Information Security & Cyber Risk Certificate.

The book’s guidance is grounded in recommendations and frameworks from relevant government agencies (NIST, CISA, and the UK’s NCSC), as well as the Center for Internet Security.

Still, the perspective I’m bringing to this subject is that of a CPA and financial planner. The book is specifically focused on what households can do to reduce their risk of fraud, account compromise, or other forms of financial harm.

A Broader Goal

I also have somewhat of a broader goal here. While the book itself is entirely focused on what the reader can do to protect themselves and their loved ones, I’m also hoping that this book can be one small piece in a broader shift toward normalizing cybersecurity discussions as part of financial planning discussions — no different than tax planning, for example.

As it stands right now, most general-audience personal finance materials don’t discuss it at all. Most financial professionals don’t discuss the topic with their clients. Financial planning training materials don’t cover it.

Cybersecurity gets left out, because it’s considered a “tech” topic rather than a personal finance topic.

That’s fine for the people who have a loved one who is savvy on these topics and willing to personally coach them. But most people don’t have that. Most people, even people trying really hard to make sure their finances are in order, are getting little to no information about cybersecurity and fraud prevention. And I believe that gap is a contributing factor to the dramatic increase in fraud that we’re seeing.

And so I hope this book will also be useful to financial professionals who recognize that cybersecurity and fraud prevention are increasingly relevant to the households they serve, but who aren’t sure what they should be telling clients.

Table of Contents

Introduction: An Epidemic of Fraud

Part One: The Threat

1. What Does a Thief Need to Access Your Financial Accounts?
2. Know Your Opponent
3. We Need Protective Policies, Because Mistakes Happen

Part Two: Fundamental Cybersecurity Concepts

4. You Are the CISO (Chief Information Security Officer)
5. The CIA Triad
6. Cryptography Basics
7. Understanding Authentication
8. Password Strength

Part Three: The Tools

9. Password Managers
10. Authenticator Apps
11. Passkeys
12. Physical Security Keys

Part Four: Policies

13. Account Configurations
14. Device Security
15. Network Security
16. Security Maintenance
17. Responding to a Cybersecurity Incident
18. Protecting Vulnerable Loved Ones

Conclusion: Layers of Protection

If you think the book might be helpful to you or a loved one, please pick up a copy:

Household Cybersecurity: a CPA’s Guide to Protecting Your Accounts and Personal Information

And if you do find it helpful, please consider posting a review on Amazon!

For More Information, See My Related Book:

Book6FrontCoverTiltedBlue

Household Cybersecurity: A CPA’s Guide to Protecting Your Accounts and Personal Information

Topics Covered in the Book:
  • Why passkeys and physical security keys are the biggest security upgrade most households haven't made yet.
  • How to choose and safely use a password manager.
  • The account settings, device habits, and network policies that actually reduce risk.
  • How to build a personal household security checklist, so good habits don't get abandoned.
  • What to do if the worst happens: a clear, step-by-step response plan.
  • How to help aging parents or other vulnerable loved ones, as well as a research finding that may surprise you about when to start.
  • Click here to see the full list.

Financial Planning Roundup: Strengths and Weaknesses of Advisor Fee-Only Models

For anybody considering hiring an advisor, it’s important to know exactly what you want. That is, it’s best if you go shopping for an advisor who meets requirements that you have selected, rather than letting somebody come to you to sell you their services.

One way in which advisors can be categorized is by what services they provide. At a very high level, the options would be:

  1. Advice-only (i.e., they provide advice but do not manage the portfolio),
  2. Portfolio management with very limited advice, or
  3. Comprehensive financial planning, together with portfolio management.

Financial planners/advisors can also be grouped by designation (CFP, CPA, PFS, CFA, EA, etc.) or by areas of expertise.

Finally, it’s important to have a good idea of what fee model(s) you’d be willing to accept. Allan Roth recently wrote a piece discussing the pros and cons (from the client perspective) of the various fee-only (i.e., non-commission) models:

Other Recommended Reading

Thanks for reading!

Ways that Owning Individual Stocks Can Go Wrong

Most of the time, when people buy individual stocks (or choose not to sell ones that they already own), the thought process appears to be something along the lines of: I expect that this company will earn lots of profits in the coming years.

But that’s not a good enough reason to buy an individual stock. (Nor is it a good enough reason to choose not to sell a stock that you already own.)

Choosing to allocate anything more than a trivial portion of your portfolio to an individual stock means taking on considerable additional risk, relative to simply owning a diversified fund of stocks. So you need to have a strong reason to think that this particular stock will earn better returns than the overall market.

And, what most people don’t know is that the performance of a given stock is not determined by whether the underlying company performs well or poorly. Rather, it is determined by whether the underlying company does better or worse than the market expected it to do. There is, therefore, little to be gained from picking individual stocks unless you have some unique insight about the company which the broader overall market does not have — something that isn’t already “priced in.”

A quick litmus test: have you even attempted a financial analysis of the company? Have you looked at their financial statements? Have you done any financial modeling at all? If not, you owe it to yourself to be honest about what you’re doing. You’re investing based on vibes. And you’re pitting that approach, and your money, against professionals who are taking a considerably more rigorous approach to the process.

Another hurdle: if you do think you have a unique insight into this company’s future profitability, it’s important to make sure that you won’t be running afoul of insider trading rules if you make any trades based on the information you have.

But even from that point (i.e., you firmly believe you have a unique insight into the company’s future profitability, and you’re confident that it’s not based on insider information), there are still multiple ways that it can go wrong.

The unique insight you have about the company could turn out to be wrong. A common version of this is, “right line of business, wrong company.” You successfully identified a line of business that grew much faster than the market expected, but the specific company you chose turned out not to be the winner in that industry.

Alternatively, the unique insight you have about the company could turn out to be right, but you were wrong about it being unique. In other words, the market already knew, and the information was already baked into the price.

Another possibility: the unique insight you have about the company turns out to be right, but you weren’t accounting for some negative factor that the market was accounting for (and you were thus overvaluing the stock).

And finally: the unique insight you have about the company turns out to be right, but neither you nor the market was accounting for a negative factor that turned out to be important (i.e., everybody was overvaluing the stock).

Disclaimer: By using this site, you explicitly agree to its Terms of Use and agree not to hold Simple Subjects, LLC or any of its members liable in any way for damages arising from decisions you make based on the information made available on this site. The information on this site is for informational and entertainment purposes only and does not constitute financial advice.

Copyright 2026 Simple Subjects, LLC - All rights reserved. To be clear: This means that, aside from small quotations, the material on this site may not be republished elsewhere without my express permission. Terms of Use and Privacy Policy

My Social Security calculator: Open Social Security